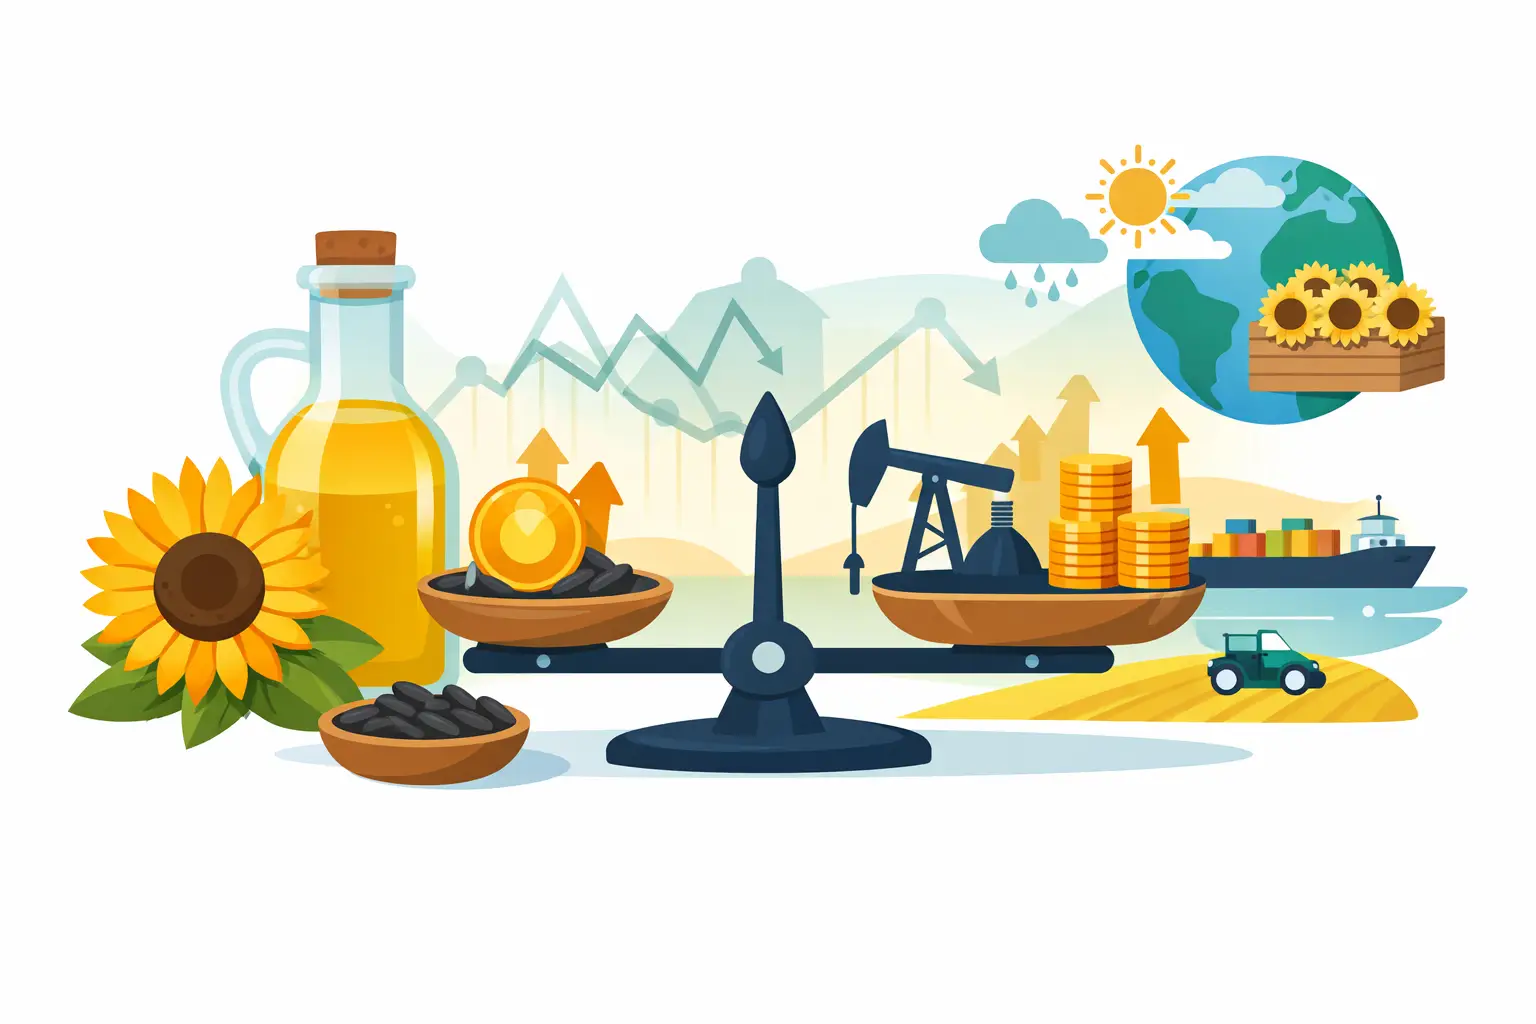
A small shift in seed yield, freight cost, or export policy can move sunflower oil prices faster than many buyers expect. For importers, distributors, and food manufacturers, understanding what affects sunflower oil pricing is less about theory and more about timing contracts, managing margin, and protecting supply continuity.
Sunflower oil is a commodity, but it does not move on one variable alone. Price formation reflects agricultural output, industrial processing, logistics, global vegetable oil competition, and regional risk. In practice, buyers who track these drivers can read the market more accurately and make better purchasing decisions.
What affects sunflower oil pricing in the physical market
The first driver is sunflower seed availability. If planted acreage is high, weather conditions are favorable, and harvest quality is strong, crushers have better raw material access. That usually supports more stable oil pricing. If drought, excessive rain, frost, or disease reduce yield or oil content, the cost base rises quickly.
Seed quality matters almost as much as seed volume. Two harvests may look similar on paper in terms of tonnage, but if one season produces lower oil recovery, processors need more seed to produce the same output. That changes crushing economics and affects the price offered to bulk buyers.
Regional concentration also matters. Ukraine has long held a central role in global sunflower production and processing. When a large producing origin faces disruption, the market does not simply replace those volumes overnight. Alternative supply may exist, but often at different cost levels, different lead times, and different quality or contract terms.
Agricultural supply is the base layer
Crop fundamentals remain the base layer for price. Acreage decisions are influenced by expected returns compared with corn, wheat, soybeans, or rapeseed. If growers shift land to other crops because input costs or expected margins look better elsewhere, future sunflower seed availability can tighten.
Weather is the most visible variable, but input economics also play a large role. Fertilizer, crop protection, diesel, and financing costs all shape the economics of planting and harvesting. When farm-level costs increase, seed prices usually need to rise to keep production attractive. That pressure eventually moves through the value chain into crude and refined sunflower oil.
Harvest timing creates its own pattern. Immediately after harvest, stronger physical availability can ease short-term pressure if logistics are functioning normally. Later in the season, pricing may firm as inventories are drawn down, especially if export demand remains active or if there are concerns about the next crop.
Processing costs and refining spreads
Sunflower oil pricing is not determined by seed costs alone. Industrial processing adds another layer. Crushing margins depend on the relationship between seed prices, oil values, and by-product values such as meal. If processors face weak by-product demand or compressed margins, they may become less aggressive in the market or adjust output accordingly.
Energy cost is especially relevant. Oil extraction, refining, winterization, storage, and packaging all require power and fuel. When natural gas, electricity, or industrial fuel prices rise, processing costs increase. In periods of energy volatility, even a stable seed market can still produce firmer oil offers.
Refining level also changes the commercial price. Crude sunflower oil, refined sunflower oil, and bottled retail-ready product carry different cost structures. Bulk B2B buyers already understand this distinction, but it remains a common source of pricing differences across suppliers. Product specification, quality parameters, and destination requirements all affect the final number on an offer sheet.
Freight, storage, and port conditions
Logistics often move prices as much as crop data. Inland transportation from farm to crush plant, then from plant to terminal or port, adds cost at every stage. Trucking shortages, rail constraints, fuel spikes, storage congestion, and port delays all influence final export pricing.
Ocean freight is another major variable for international buyers. A favorable oil price at origin can become less competitive once freight is added, especially for long-haul destinations. That is why buyers usually evaluate landed cost, not just FOB or ex-works numbers.
Port accessibility matters as well. If export corridors tighten, inspection times increase, or insurance premiums rise, sellers build those risks into price. In commodity trade, friction in logistics rarely stays isolated. It quickly becomes part of the market.
Trade policy, currency, and regional risk
Trade policy can change price direction quickly. Export restrictions, import duties, sanitary requirements, and regulatory changes all affect supply flow. Even when no formal restriction is introduced, the market often reprices in anticipation of policy action.
Currency movement also matters because sunflower oil is traded internationally while many operating costs are local. If the producing country’s currency weakens, exporters may gain flexibility in dollar terms. If it strengthens, offers may rise. For buyers working in the US market, exchange rate effects are not always obvious at first glance, but they are built into supplier pricing logic.
Regional risk is another pricing factor that cannot be ignored. Political instability, conflict, infrastructure disruption, and financing constraints raise operational uncertainty. In those conditions, prices reflect not only the physical cost of making and shipping oil, but also the risk premium attached to fulfilling contracts reliably.
Competition from other vegetable oils
Sunflower oil does not price in isolation. Buyers compare it with soybean oil, palm oil, and rapeseed oil based on application, label preference, functionality, and cost. When one competing oil becomes significantly cheaper, some industrial demand shifts. That can pressure sunflower oil pricing, even if sunflower fundamentals themselves have not changed.
The reverse is also true. If palm oil supply tightens or soybean oil rallies sharply, sunflower oil may become relatively more attractive, supporting stronger demand and firmer prices. This cross-market relationship is one of the most important factors procurement teams monitor.
Substitution is never perfect. Food manufacturers have formulation requirements, sensory targets, and customer expectations. Still, at scale, relative pricing across the edible oils complex influences demand allocation. A buyer sourcing for frying, manufacturing, or private label production may adjust volume between oils if the spread becomes too wide.
What affects sunflower oil pricing from the buyer side
Demand behavior affects price as much as supply behavior. When buyers enter the market at the same time, especially after a period of delay, suppliers can see order books fill quickly. That often firms up nearby pricing. When buyers hold back because they expect lower prices, the market can soften temporarily, but that strategy carries its own risk if supply tightens faster than expected.
Contract structure matters here. Spot buying may capture short-term dips, but it also exposes buyers to sudden price increases and availability gaps. Longer-term contracts can improve continuity and planning, although they may not always catch the lowest point in the market. The right approach depends on volume needs, inventory strategy, and margin sensitivity.
Specification also influences demand-side pricing. Standard refined bulk oil has a different market profile than customized packing, private-label formats, or destination-specific documentation requirements. The more tailored the commercial package, the less useful it is to compare prices on a simple headline basis.
Reading price moves more accurately
For procurement teams, the most practical approach is to watch several indicators at once. Seed crop outlook tells you about the raw material base. Processing economics show whether output is commercially attractive. Freight and port conditions indicate whether supply can move efficiently. Competing vegetable oil markets help explain substitution pressure. Policy and regional developments show whether risk premiums are likely to expand.
No single factor explains every move. A large harvest can still coincide with firm prices if freight is expensive, energy costs are high, or global edible oil demand is strong. A weaker demand period can still leave prices elevated if supply risk remains significant. That is why sunflower oil pricing should be read as a chain of connected costs and risks, not as a one-variable commodity.
For buyers sourcing from experienced producers, price should be assessed alongside execution. The lowest number on paper does not always deliver the best commercial result if lead times slip, quality varies, or documentation and shipment performance are inconsistent. In B2B edible oils, price matters, but dependable supply matters with it.
EKOBIOTEK operates in a market where these variables are active every season, and serious buyers usually evaluate offers with that full context in mind. The better question is not only where price is today, but which underlying factor is most likely to move it next.